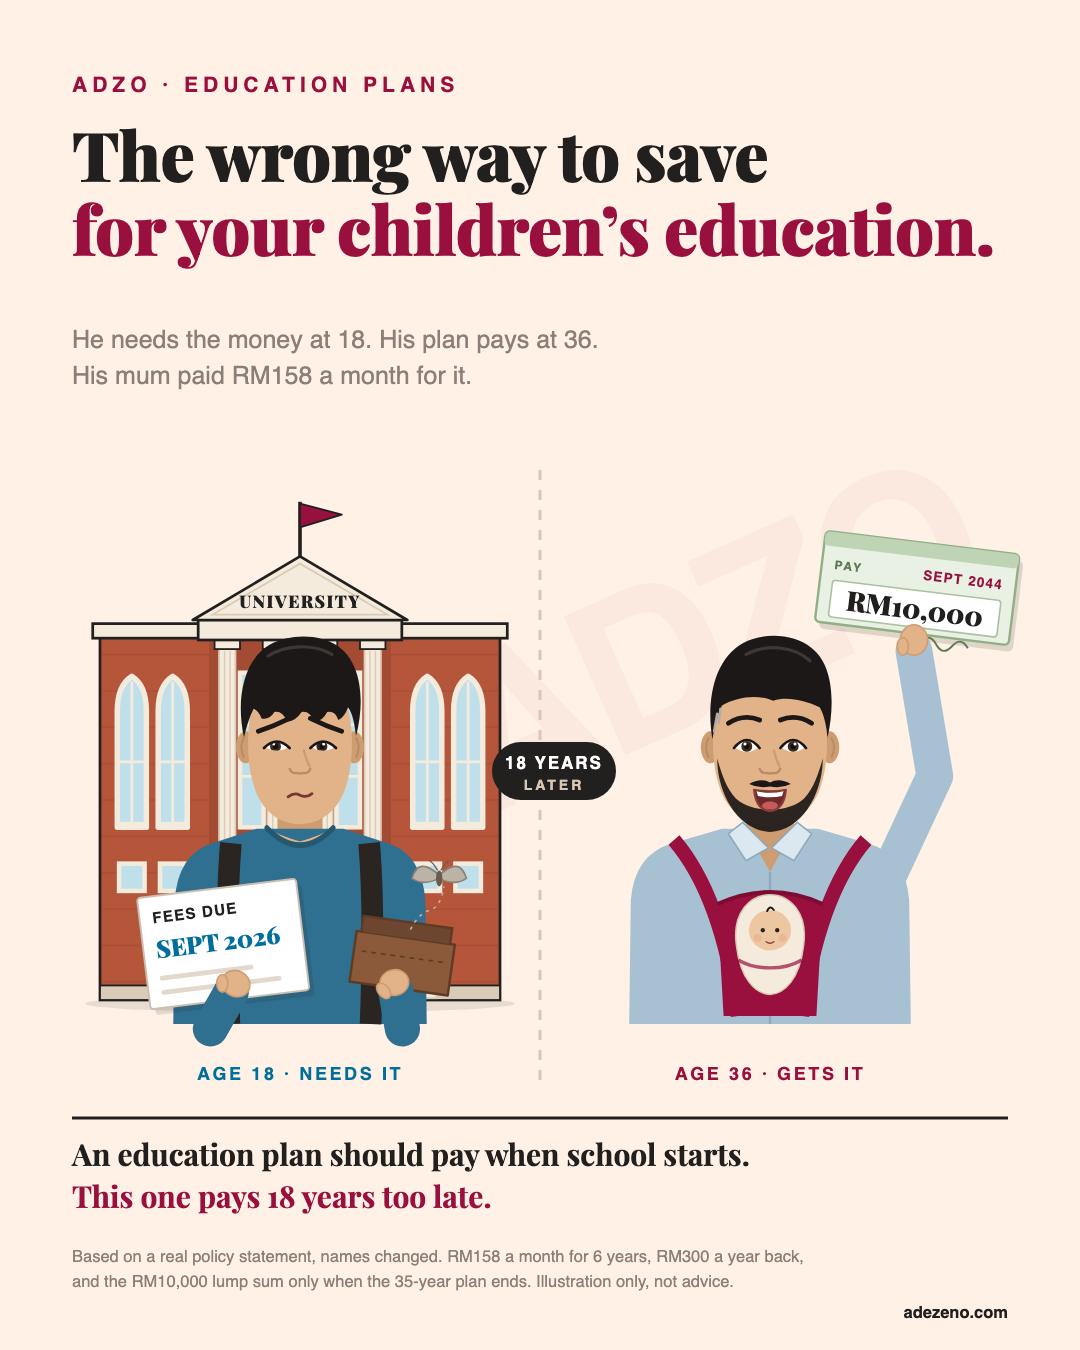
The wrong way to save for your children’s education.
He needs the money at 18. His education plan pays at 36.
His mum paid RM158 a month for it.
Here’s what went wrong, and what I’d do instead.
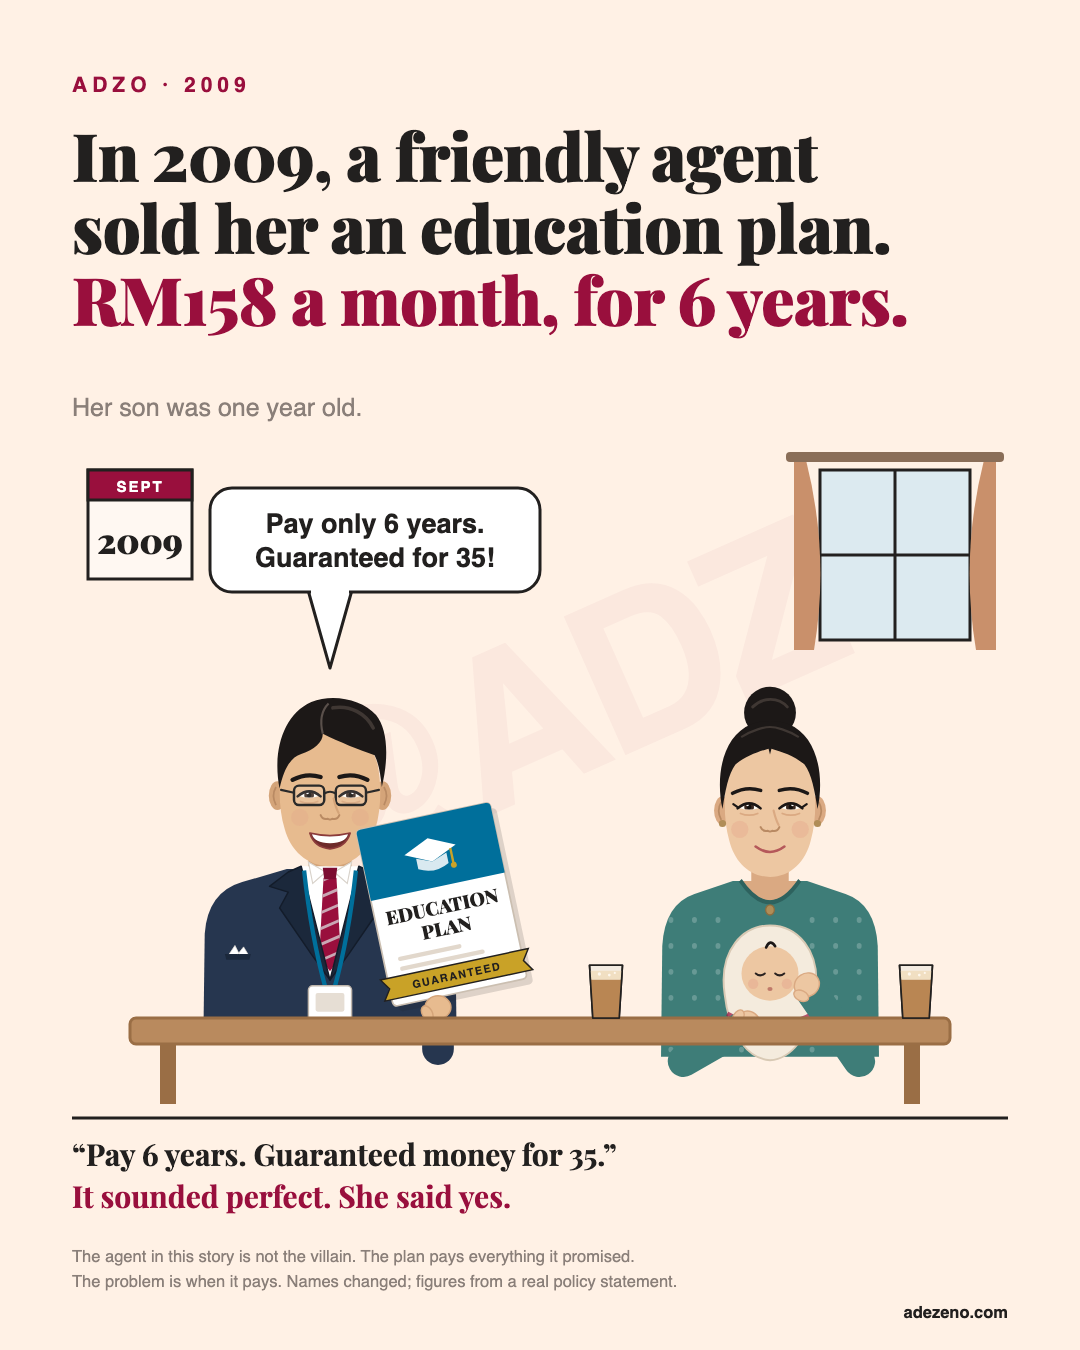
In 2009, a friendly agent sold her an education plan.
RM158 a month, for just 6 years. Guaranteed money for 35 years.
It sounded perfect. She said yes.
The agent isn’t the villain. The plan does what it promised.
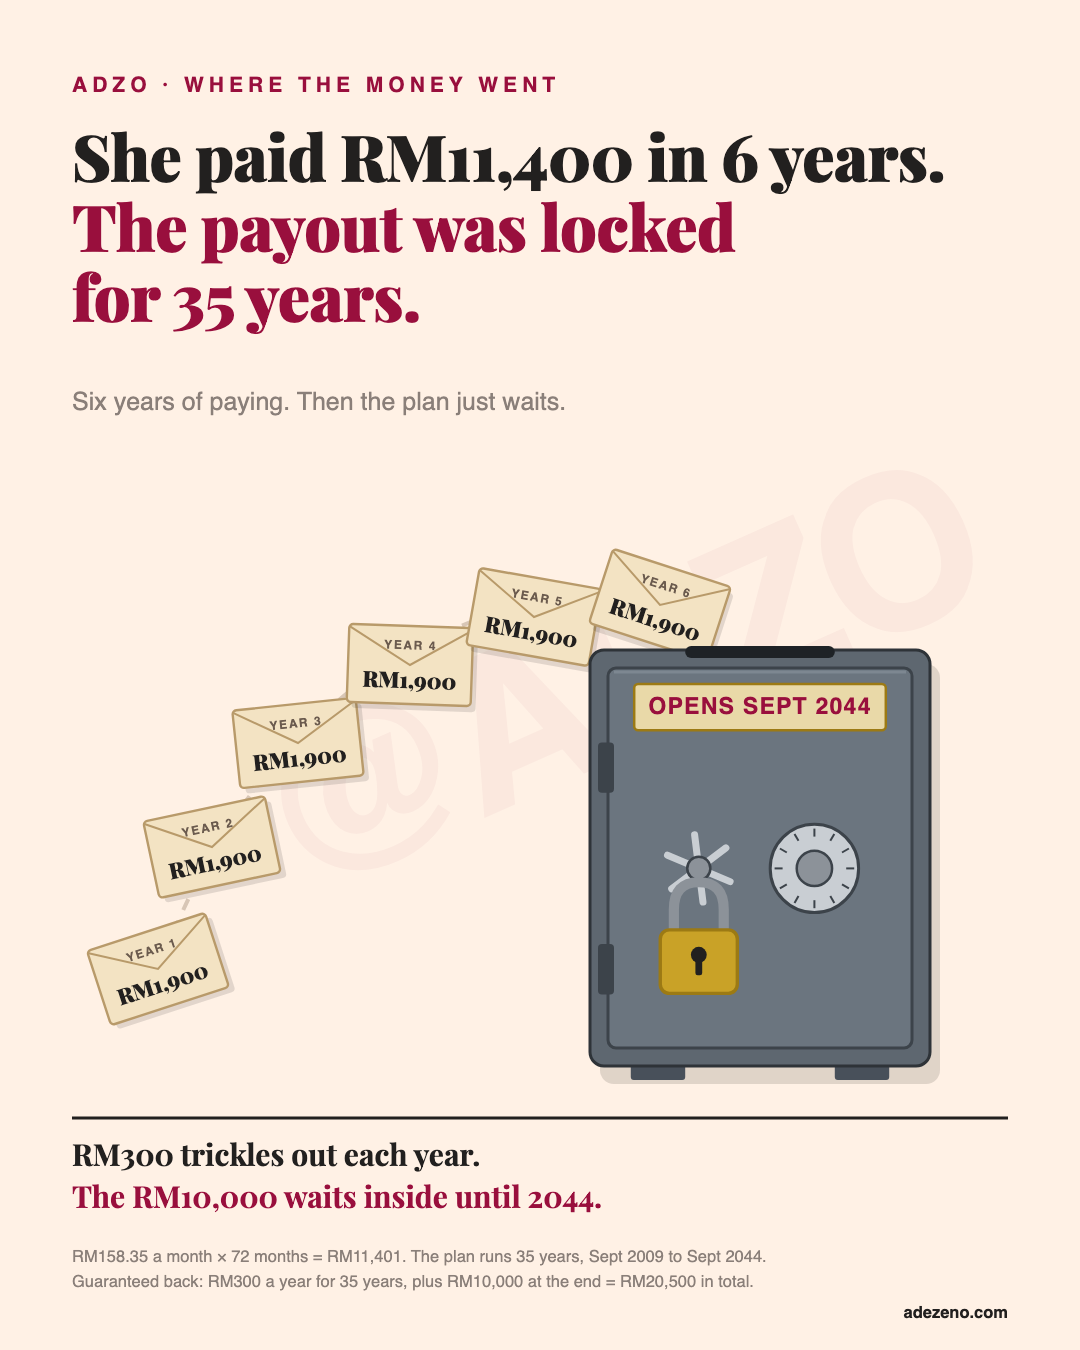
She paid RM11,400 in 6 years. The payout was locked for 35.
Six years of paying: about RM11,400 in.
Then the plan waits. It pays out RM300 a year.
The big RM10,000 stays inside until the very end.
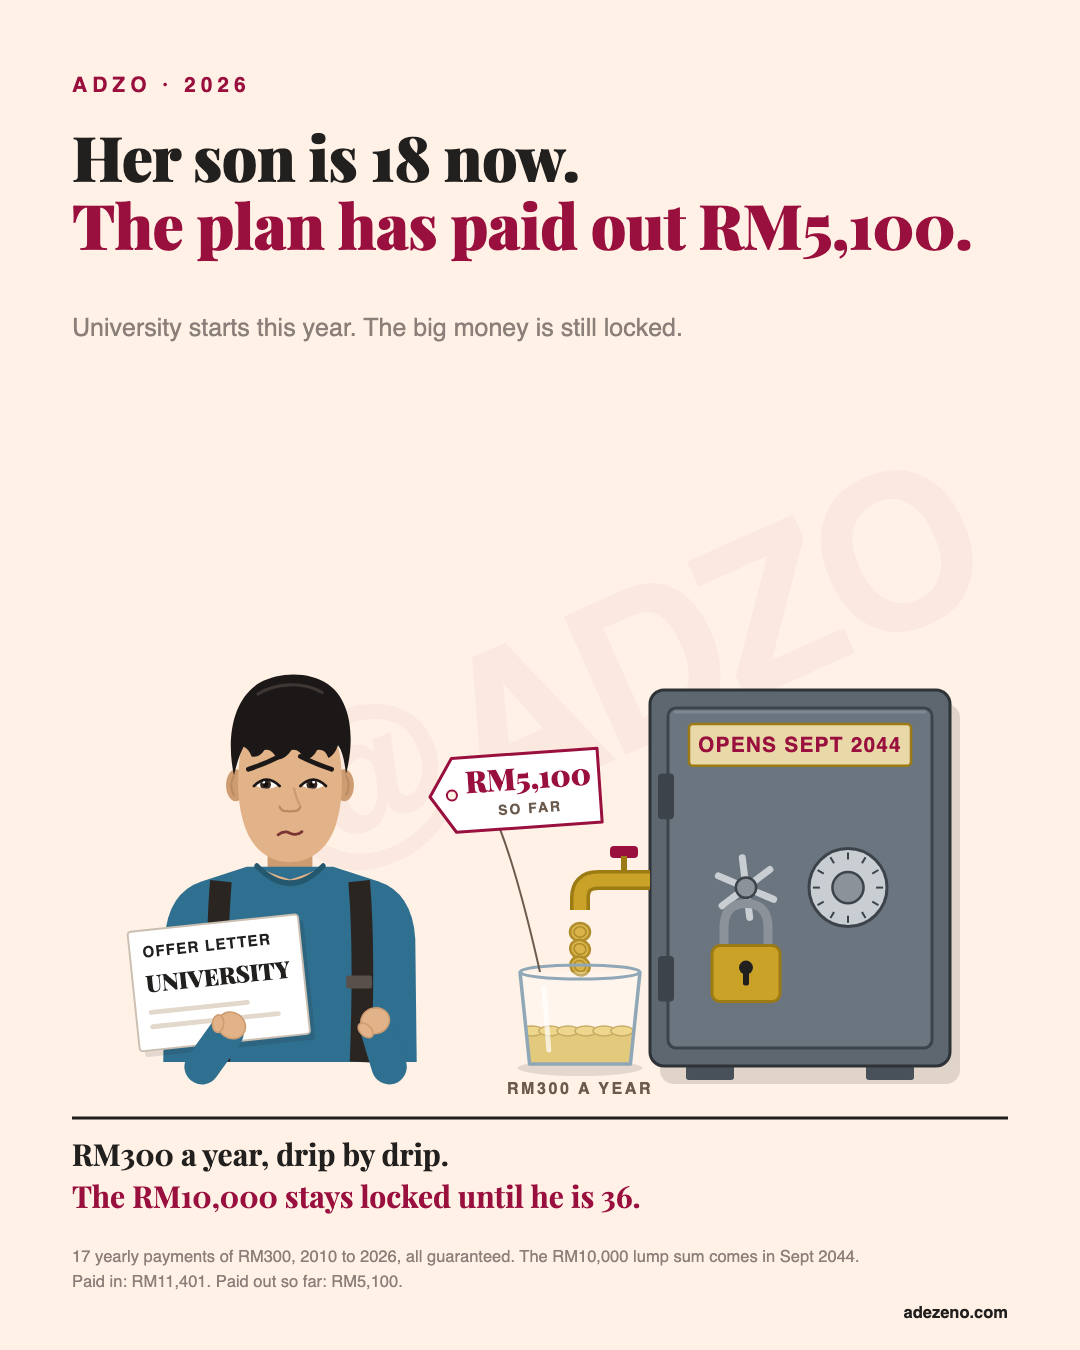
Her son is 18 now. The plan has paid out RM5,100.
University starts this year.
The plan has dripped out RM300 a year: about RM5,100 so far.
The RM10,000 stays locked until he is 36.
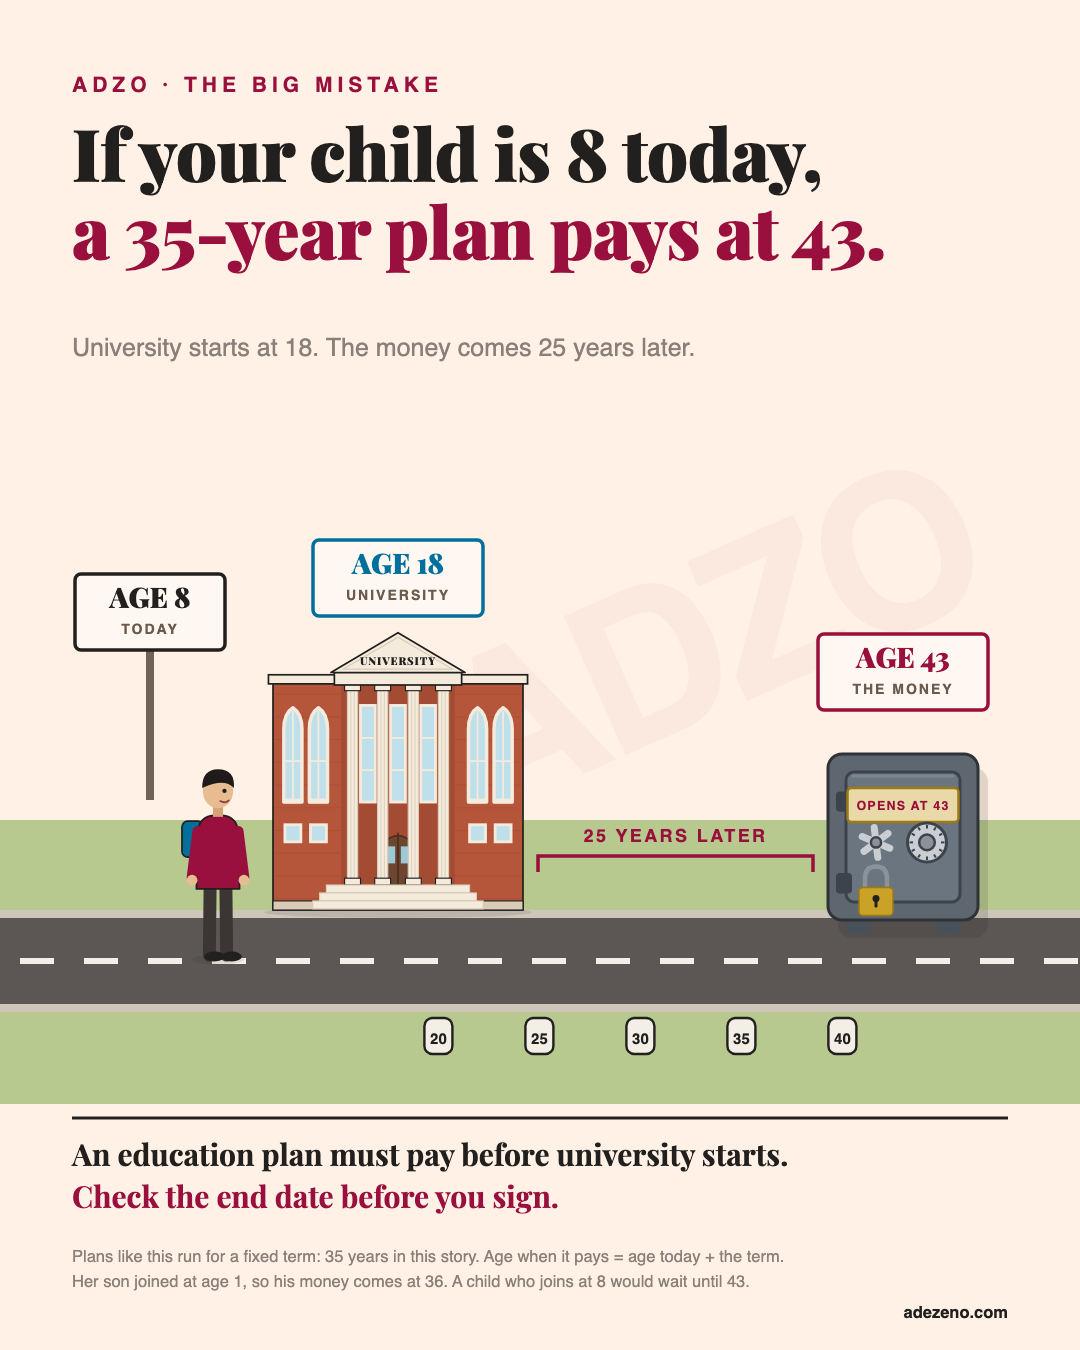
If your child is 8 today, a 35-year plan pays at 43.
Here’s the big mistake: the lock is longer than childhood.
University comes at 18. With a 35-year plan, the money comes 25 years later.
Always check the end date before you sign.
Before buying the same plan for her daughter, she showed it to me.
Her daughter is 12. She was about to buy the same plan again.
First she asked me: is this a good plan?
So I gave it a report card.
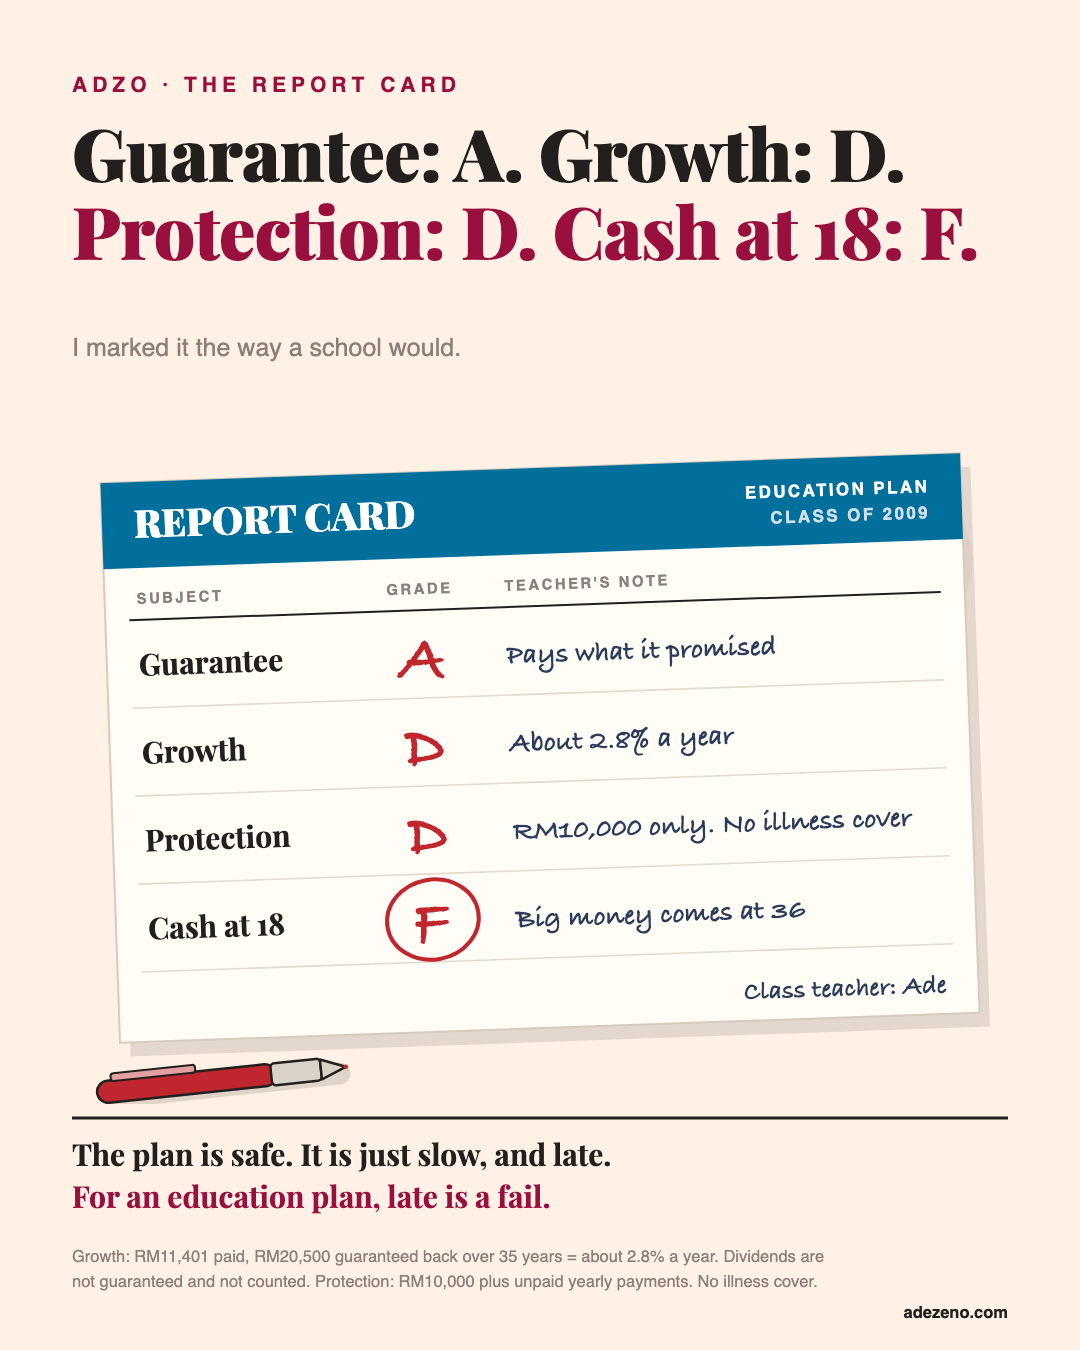
Guarantee: A. Growth: D. Protection: D. Cash at 18: F.
The plan is safe. It pays what it promised.
But it grows slowly, about 2.8% a year. And it pays nothing for a serious illness.
The big money comes at 36. For an education plan, that’s a fail.
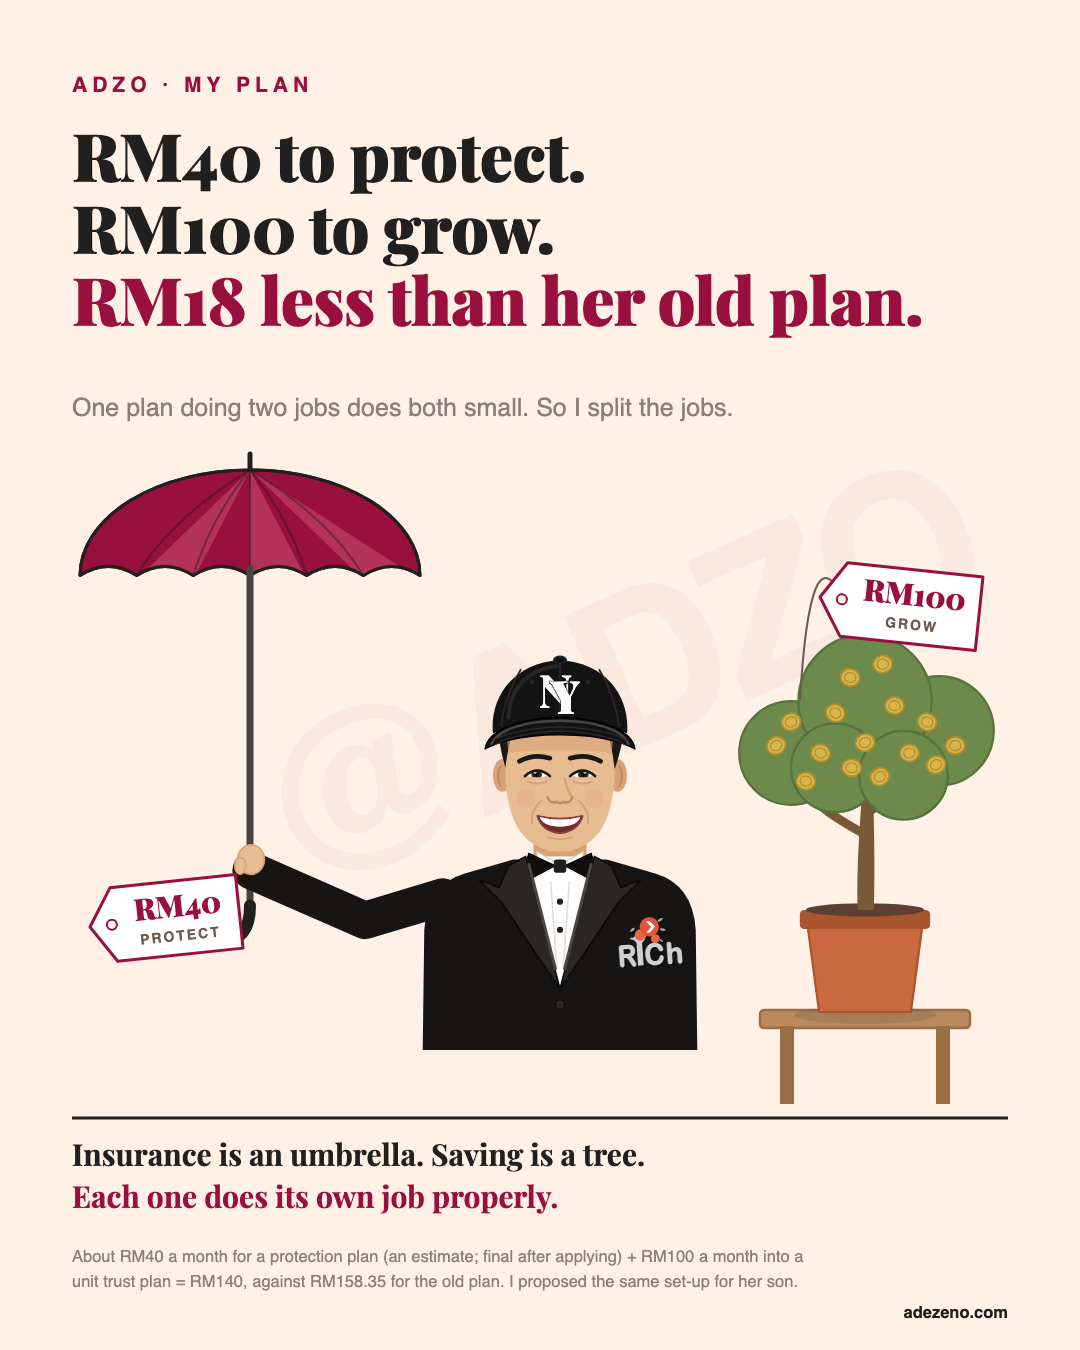
RM40 to protect. RM100 to grow. RM18 less a month.
Insurance is an umbrella. Saving is a tree.
One plan trying to be both gives you a small umbrella and a small tree.
So I split the jobs: about RM40 for protection, and RM100 into a monthly unit trust plan.
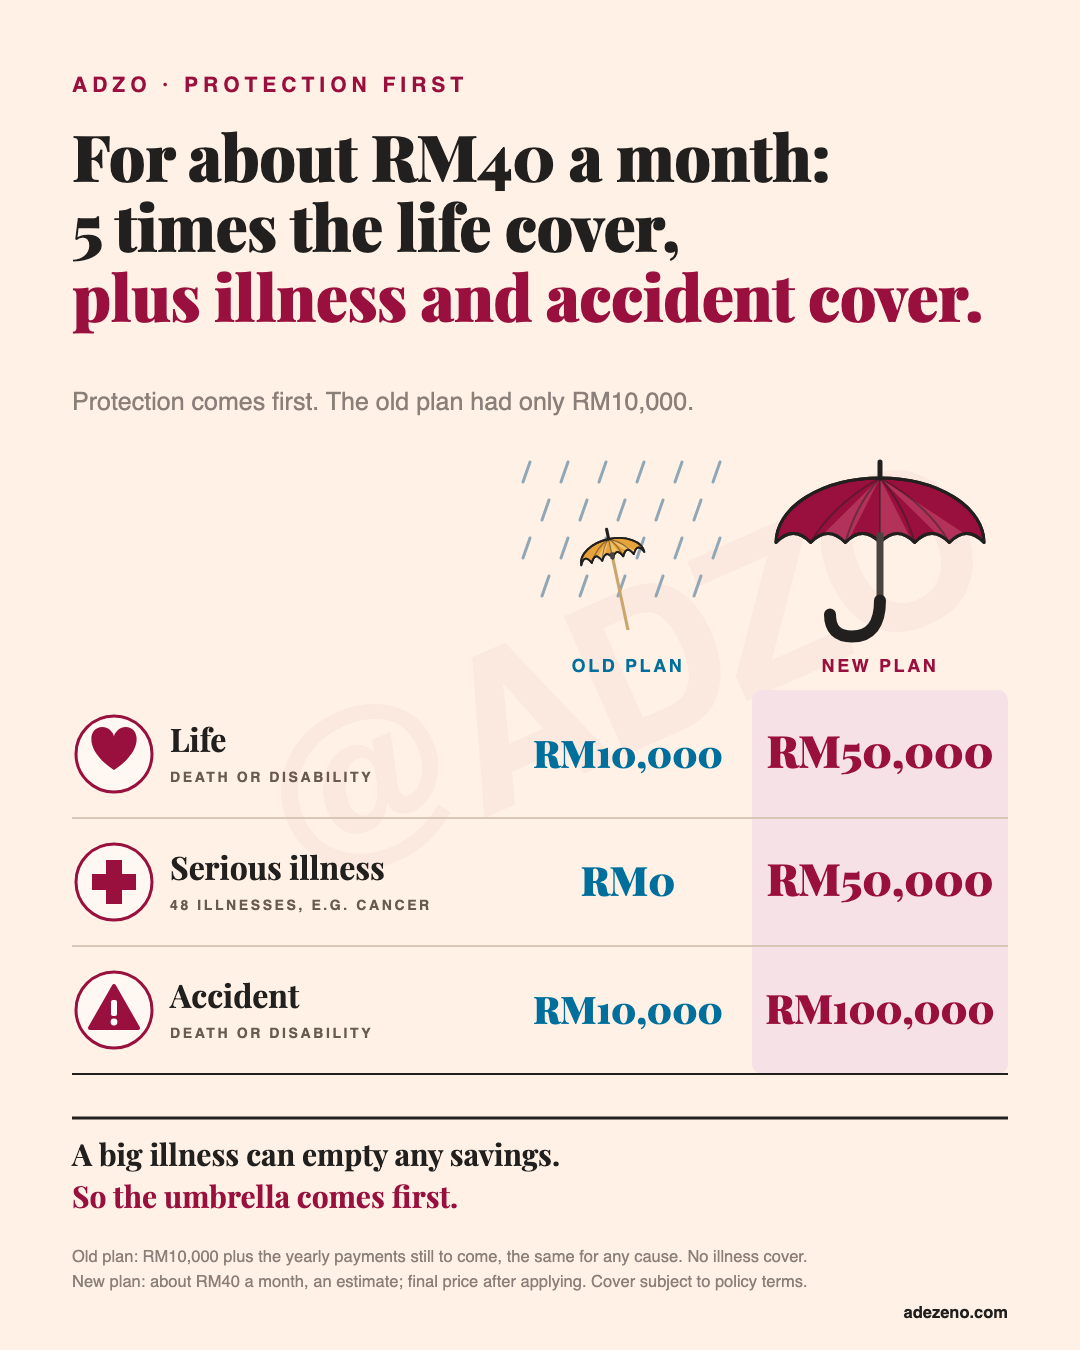
For about RM40 a month: 5 times the life cover, plus illness and accident cover.
Life: RM10,000 before. RM50,000 now.
Serious illness: RM0 before. RM50,000 now.
Accident: RM10,000 before. RM100,000 now.
Protection comes first. A big illness can empty any savings.
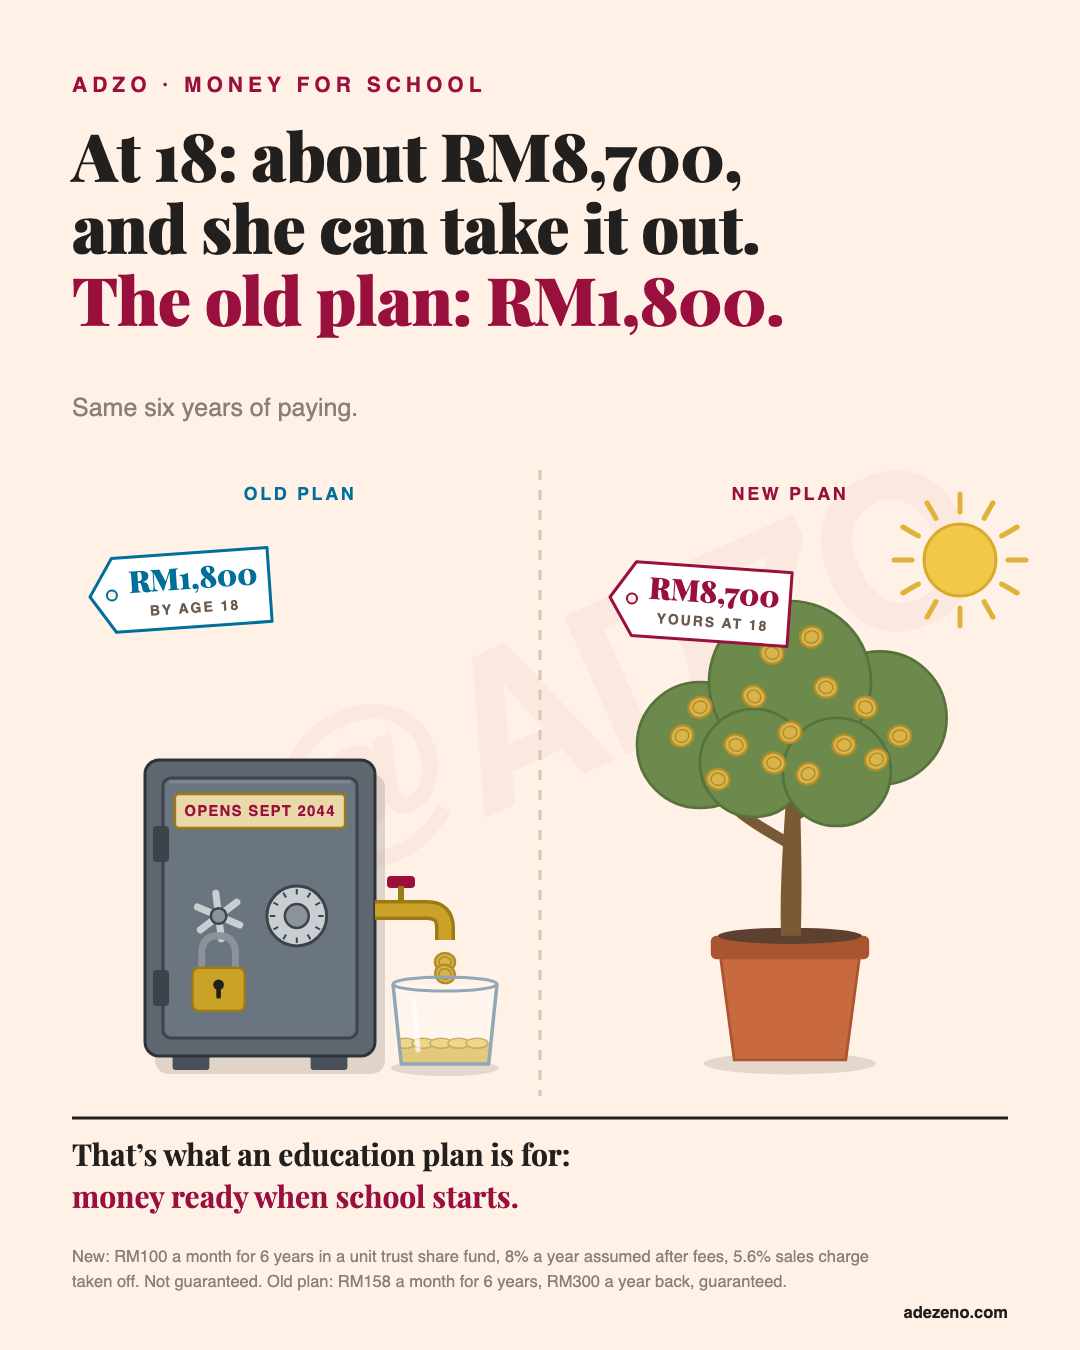
At 18: about RM8,700, and she can take it out. The old plan: RM1,800.
Same six years of paying.
Her savings could be about RM8,700 when she turns 18. And she can use it for university.
That’s what a small monthly amount can do when it’s left to grow.
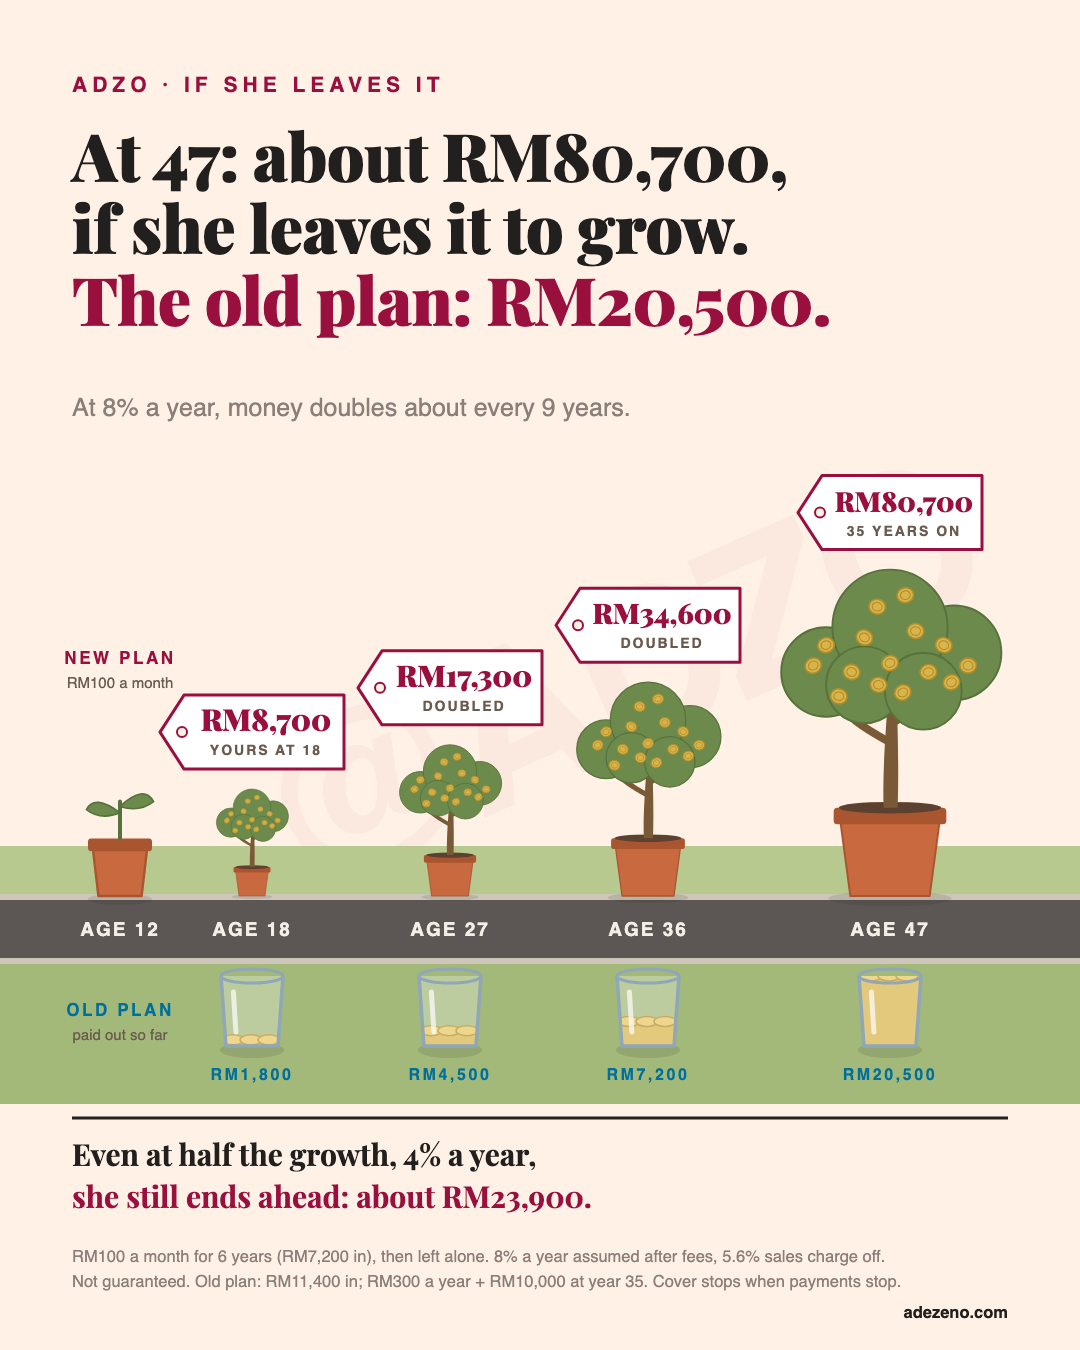
At 47: about RM80,700 if she leaves it to grow. The old plan: RM20,500.
At 18 she can use the money. Or she can leave it alone.
Left alone at 8% a year, it doubles about every 9 years. By 47: about RM80,700.
The old plan pays RM20,500 in all. Even at 4% a year, hers still ends ahead: about RM23,900.
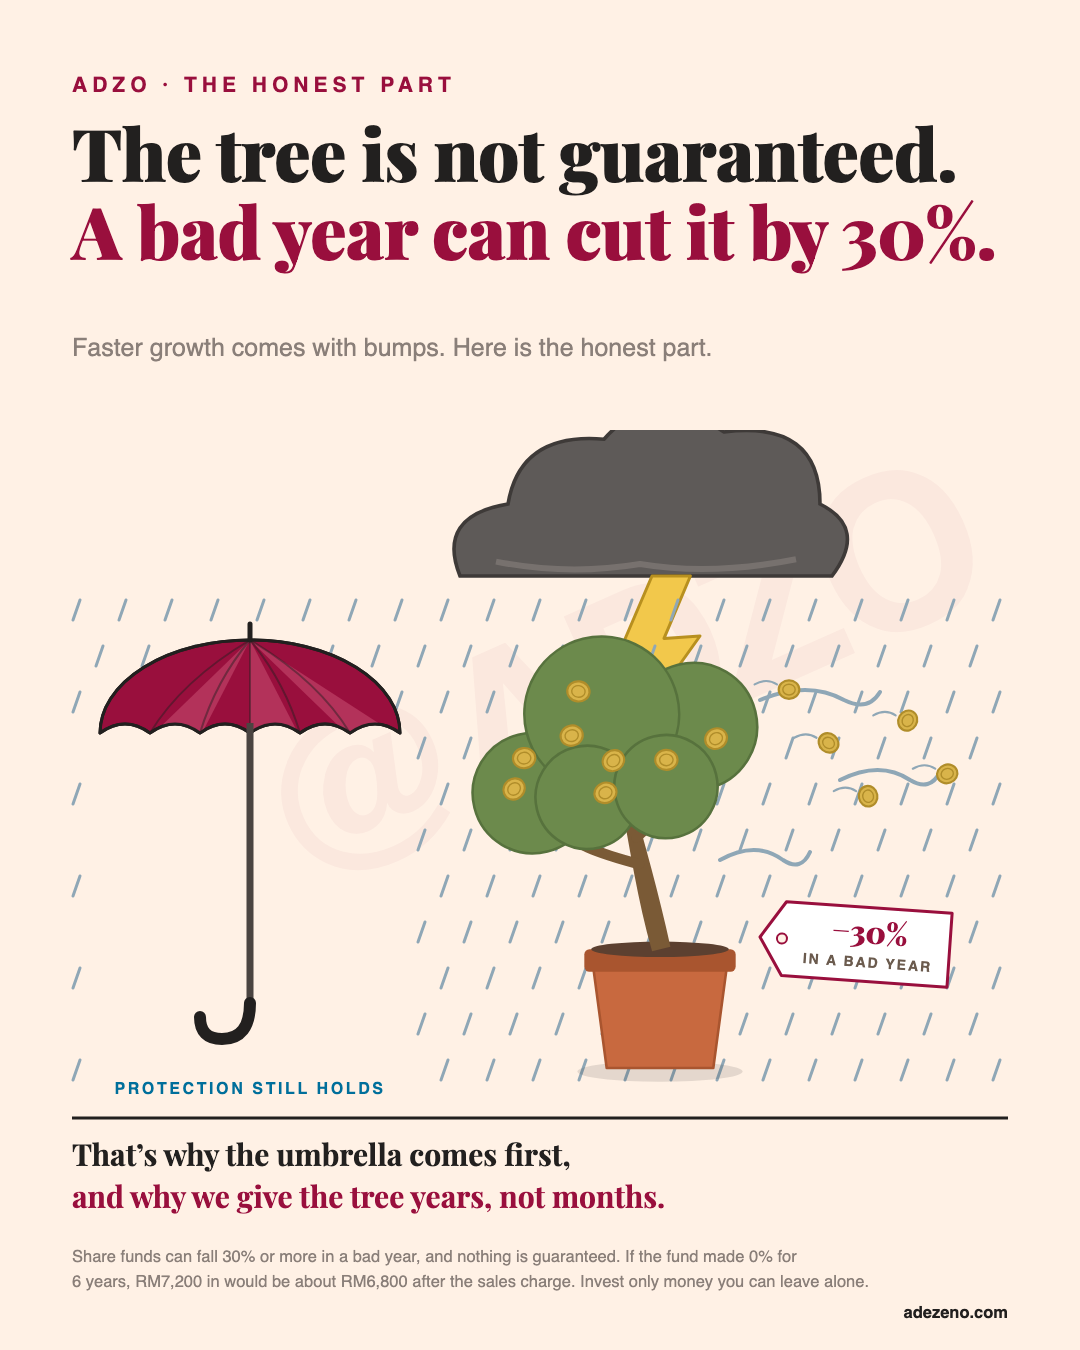
The honest part: the tree is not guaranteed. A bad year can cut it by 30%.
A share fund can drop a lot in a bad year. Nothing about it is guaranteed.
That’s why the umbrella comes first. And why we give the tree years, not months.
What to do when your fund falls is a story of its own.
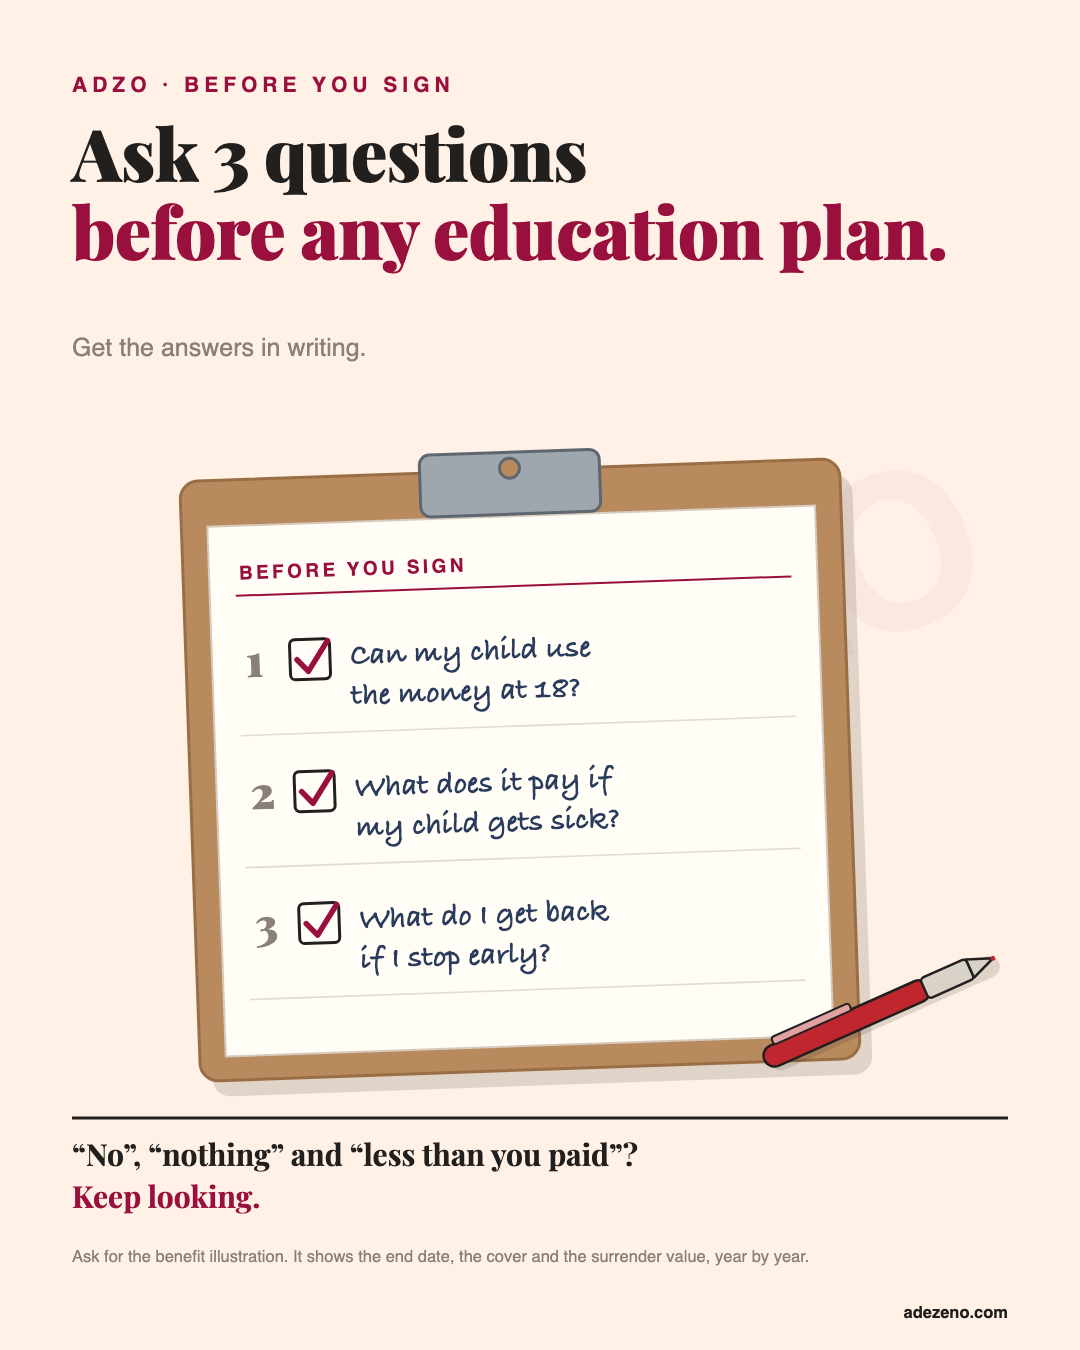
Ask 3 questions before any education plan.
1. Can my child use the money at 18?
2. What does it pay if my child gets sick?
3. What do I get back if I stop early?
No, nothing, and less than you paid? Keep looking.
Already have a plan like this? Don’t cancel it. Send me the statement first.
Cancelling early usually gives back less than you paid.
The costly years may already be behind you.
Send me a photo of your statement. I’ll give it a report card.
Send me your statement on WhatsApp → Or see how I work with clientsThis is general information for education, not personal financial advice. The story is based on a real policy statement, with names and small details changed. The new-plan figures are illustrations: about RM40 a month for protection (an estimate; the final premium is set after applying) and RM100 a month into a unit trust share fund with a 5.6% sales charge and an assumed 8% a year after fees, which is not guaranteed. Unit prices can fall as well as rise, and past performance does not indicate future returns. Insurance cover is subject to the policy's terms, exclusions and underwriting. Do not cancel an existing policy without checking what you would lose. Speak to a licensed consultant about your own circumstances before acting. Adezeno is a licensed Unit Trust Consultant with Eastspring Investments Berhad, FiMM No. F01029300.